Year-End Tax and Cash Planning for Firearms Retailers
Counter, Range and Back Office Tips
** The following article is for informational purposes only. Please consult with your own tax preparer or verify before relying on information presented here. **
Independent firearms retailers manage a business unlike any other in retail. Inventory is serialized, regulated and valuable. Demand swings sharply with news cycles and elections. Many dealers also run indoor ranges, teach classes, sell memberships, offer gunsmithing and handle transfers, each with different revenue patterns and tax issues. The back office often gets attention only when the ATF or the tax return forces it.
Year end is the time to change that. Decisions made before December 31 on inventory, equipment, payroll and cash can lower taxes legally and leave the store in a stronger position for the year ahead. The 2025 federal tax law, commonly called the One Big Beautiful Bill Act (OBBBA), changed several rules that matter to dealers and range operators. This article outlines the items to review now. It is general information rather than advice for a specific business.
1. Inventory: count it, value it and document it
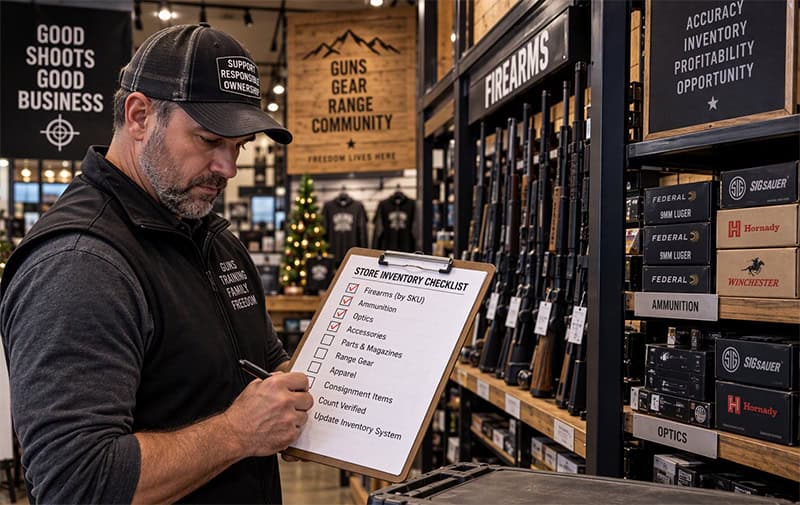
For most dealers, inventory is the largest asset and the biggest driver of taxable income. Your acquisition and disposition records already track every firearm by serial number, which gives you an advantage at count time. Reconcile the bound book or electronic A&D records to the point-of-sale system and the general ledger, and count accessories, optics, ammunition and apparel physically.
Valuation. Retailers with average annual gross receipts of $32 million or less for 2026 (measured over the prior three years) can generally use simplified inventory methods and are exempt from the uniform capitalization rules. Most independent dealers qualify. Inventory cost includes freight-in and any duties on imported products.
Write-downs. Discontinued models, damaged accessories and aging stock can generally be valued below cost only when they are actually offered for sale at reduced prices within 30 days after the inventory date, or disposed of. A general reserve for slow-moving inventory is usually not deductible. If demand has cooled since a buying surge, a pre-year-end sale both raises cash and supports a write-down.
Used guns and trade-ins. Firearms taken in trade are inventory at the value assigned in the trade. Keep trade-in records consistent between the A&D book and accounting system.
Consignment. Firearms held on consignment remain the consignor’s property until sold and should not be included in your inventory. Consignment sales should be recorded separately, with only your commission as revenue if you act as agent.
2. Layaway, special orders and deposits
Layaway and special-order deposits are common in firearms retail, especially for higher-end guns and NFA items with long approval waits. Customer deposits are generally not income until the sale is completed for accrual-basis retailers, but advance payment rules can require income recognition by the year after receipt in some cases. Keep a clean schedule of deposits, refund obligations and expected delivery dates. Deposits for NFA items awaiting approval should be tracked separately so they are not recognized as sales prematurely.
3. Gunsmithing, builds and federal excise tax
The federal firearms and ammunition excise tax, 10% on pistols and revolvers and 11% on other firearms and ammunition, is imposed on manufacturers, producers and importers, not on retailers. But dealers who also build, assemble or substantially modify firearms for sale may become manufacturers for excise tax purposes. Manufacturers that produce fewer than 50 firearms in a calendar year are generally exempt from the tax on firearms, but the rules are technical and ammunition reloading for sale is treated separately.
Dealers that hold a manufacturing license or perform custom builds should review their activity with an adviser, confirm whether excise returns are required and keep records of the number of firearms produced each year. Excise tax mistakes can carry penalties and interest that easily exceed the tax itself.
4. Ranges, fixtures and equipment
For property acquired and placed in service after January 19, 2025, the law permanently restored 100% bonus depreciation. Display cases, gun racks, safes, security systems, point-of-sale terminals, computers, range target systems and much of the equipment used in an indoor range can generally be deducted in full in the year it is placed in service. The IRS explains the rules in its guidance on the additional first-year depreciation deduction, and IRS Publication 946 covers recovery periods.
Ranges raise special classification questions. Ventilation systems, ballistic baffles, bullet traps and lane dividers may be building components with long recovery periods, equipment with short ones, or qualified improvement property, depending on how they are installed and whether the space is leased. A cost segregation study can sort these components for a newly built or renovated range and often produces a substantial first-year deduction. Interior improvements to a leased store, such as new lighting, flooring and walls, are often qualified improvement property, a 15-year category eligible for bonus depreciation.
Section 179 expensing is also available, with a 2026 limit of $2,560,000, phasing out above $4,090,000 of purchases. Several states do not follow federal bonus depreciation, so check state rules before expensing everything.
The $2,500 de minimis safe harbor lets businesses without audited financial statements expense items costing $2,500 or less per invoice or item, if they elect the safe harbor and follow a consistent written policy. Rental firearms used on the range, cleaning equipment and smaller fixtures often fit. Rental guns that will be used for years can also be treated as depreciable equipment rather than inventory once they are placed in service as rentals.
5. Range memberships, classes and gift cards
Annual range memberships, prepaid lane packages, class registrations and gift cards are all paid in advance. Accrual-basis businesses can generally defer advance payments to the next tax year to the extent they are deferred for financial statement purposes, but no further. A membership sold in December 2026 may therefore be partly reported in 2027. Cash-basis businesses generally report the income when received.
Gift cards may also be subject to state unclaimed property laws, so check your state’s rules before treating unredeemed balances as income.
6. Payroll, overtime and instructors
Gun counters and ranges often get busiest at unpredictable times, and overtime follows. Beginning with 2025, eligible employees may deduct up to $12,500 ($25,000 for joint filers) of qualified overtime compensation on their own returns, subject to income phase-outs. Only the premium portion of overtime required by the Fair Labor Standards Act counts. For 2026, employers report qualified overtime on Form W-2 in Box 12 using code TT. Payroll systems should separate FLSA overtime from other premiums and bonuses.
Firearms instructors, range safety officers and gunsmiths are sometimes paid as independent contractors. Classification depends on control, the relationship and how the work is performed, not on the label in a contract. Instructors who teach on your schedule, use your curriculum and your facility may well be employees.
For contractors, the Form 1099-NEC threshold rises to $2,000 for payments made in 2026, after remaining at $600 for 2025 payments. Collect Forms W-9 from instructors and vendors now. The IRS page on whether a Form 1099 is required explains the rules. A reliable payroll service can help manage overtime coding, seasonal staff and contractor reporting.
7. Payment processing and Form 1099-K
Firearms retailers sometimes face higher processing costs or limited processor options. Shop rates across providers at least once a year and review whether surcharging or cash discount programs are permitted in your state. Processing fees are deductible, but lower fees improve margins more than any deduction.
The law restored the Form 1099-K reporting threshold for payment platforms to more than $20,000 and more than 200 transactions. Fewer dealers will receive these forms from secondary processors, but all sales remain taxable. Reconcile processor deposits, chargebacks and fees to daily sales each month.
8. Sales tax and online sales
Dealers selling accessories, optics and ammunition online may create sales tax obligations in other states once they pass economic nexus thresholds. Firearms sold online usually ship to another licensee for transfer, which raises its own sourcing questions for sales tax. Some states also have special taxes or fees on firearms and ammunition sales. Review your sales by state at year end.
9. Interest, inventory financing and floor plans
Many dealers finance inventory through floor plan arrangements or lines of credit. The law restored the more generous Section 163(j) interest calculation beginning in 2025, which again adds back depreciation and amortization when computing adjusted taxable income. Most small retailers meeting the gross receipts test are exempt from the limit altogether. Review floor plan curtailment schedules before year end, because aging inventory may trigger principal payments that strain cash in January.
10. Cash flow through demand cycles
Firearms demand rises and falls with news events, legislation and elections. Dealers who bought heavily during one surge often carried excess inventory into the next lull. A 13-week cash forecast, including rent, payroll, floor plan payments, sales tax, estimated taxes and open purchase orders, helps owners decide how much to buy and when. Resources on cash flow management can help you build one.
Measuring gross margin return on inventory by category, firearms, ammunition, optics, accessories, range fees and classes, shows where cash is earning its keep. Ranges and training often produce steadier margins than firearm sales and can help smooth demand swings when gun sales slow after a surge.
11. Owner pay, QBI and retirement plans
The 20% qualified business income deduction under Section 199A is now permanent. Owners of sole proprietorships, partnerships and S corporations can generally deduct up to 20% of qualified business income, subject to limits at higher incomes. The IRS QBI deduction page summarizes the rules.
S corporation owners should confirm reasonable compensation before the last payroll run. Retirement plans can reduce taxable income and help retain experienced counter staff and gunsmiths. The IRS outlines retirement plans for self-employed people.
12. Succession and the license
Many gun shops are family businesses. The federal estate and gift tax exclusion is $15 million per person for 2026, and the law made the higher exclusion permanent with inflation adjustments. Succession for a firearms business has an extra layer: federal licenses do not simply transfer with ownership changes, and responsible persons must be updated with the ATF. A sale or transfer of ownership should be planned with both tax and licensing advisers well in advance. Guidance on advisory and business transition can help owners sequence those steps.
13. Records that protect the business
Dealers already keep meticulous regulatory records. Applying the same discipline to financial records pays off. Monthly bookkeeping that reconciles inventory, deposits, processor statements and sales tax makes year-end planning faster and reduces the risk of surprises in an audit. Professional bookkeeping services can fill the gap when owners are busy at the counter.
14. Range maintenance and lead management
Indoor and outdoor ranges carry environmental and maintenance costs that ordinary retailers never see: lead reclamation from bullet traps, filter replacements, HEPA vacuums, air monitoring and employee blood-lead testing. Routine recurring maintenance, such as filter changes and trap cleaning, is generally deductible when incurred. Larger projects that restore or upgrade a range, such as replacing an entire ventilation system or rebuilding a trap system, are more likely capital improvements.
Lead reclaimed from traps and berms is often sold to recyclers. Those proceeds are income, and they should be recorded rather than netted quietly against cleaning costs. Keeping invoices and recycler statements together makes the treatment clear. Safety programs and medical monitoring are deductible business expenses and can help control workers’ compensation premiums.
15. Theft, burglary and insurance recoveries
Gun shops are targets for burglary and smash-and-grab theft. A business loss from theft is generally deductible in the year the theft is discovered, reduced by any insurance recovery the business reasonably expects to receive. If a claim is still pending at year end, the deduction may need to wait until the amount of recovery is known with reasonable certainty. Police reports, A&D records showing the stolen serial numbers and the ATF theft report support the deduction. Insurance proceeds that exceed the tax basis of stolen inventory or equipment may create a gain, which can sometimes be deferred if the proceeds are reinvested in similar property within the replacement period.
Year end is also a good time to review insurance coverage limits, deductibles and security requirements in the policy against current inventory values, which may have changed with prices and buying patterns.
16. Employee purchases and discounts
Many dealers let employees buy firearms and gear at a discount. Discounts on merchandise that do not exceed the store’s gross profit percentage are generally a tax-free employee benefit. Discounts above that level are taxable wages. Employee purchases must still follow all federal and state transfer rules, and the accounting should record the sale at the discounted price with no separate expense.
17. Planning next year's mix
Before setting the 2027 budget, look at the business by line: new firearms, used firearms, ammunition, optics and accessories, transfers, gunsmithing, range fees, memberships, classes and rentals. Each line has a different margin, cash cycle and staffing need. Classes and memberships bring repeat visits and steadier revenue, while firearm sales bring larger tickets but more inventory risk. Owners who know which lines carry the business can decide where to invest in staff, space and equipment, and can time purchases to the tax year when the deduction is most valuable.
A short planning meeting with your accountant in December, with inventory, payroll and sales data in hand, is often enough to settle the major decisions, such as which equipment to buy before December 31, how much inventory to carry into the new year and whether owner compensation should change.
Year-end checklist for firearms retailers
1. Reconcile A&D records, POS and the general ledger, and count non-serialized inventory.
2. Mark down or dispose of aging stock and document it.
3. Separate consignment firearms from owned inventory.
4. Schedule layaway, special-order and NFA deposits.
5. Review gunsmithing and build activity for excise tax status.
6. Confirm placed-in-service dates for fixtures, range systems and rental guns.
7. Consider cost segregation for range construction or renovation.
8. Review memberships, classes and gift card liabilities.
9. Code FLSA overtime for W-2 Box 12 code TT.
10. Review instructor classification and collect W-9s.
11. Reconcile processor statements and compare processing costs.
12. Review sales tax obligations by state.
13. Check floor plan curtailments and build a cash forecast.
14. Review owner pay, retirement plans, QBI and succession, including licensing.
Final thought
Firearms retailers succeed by being careful, compliant and responsive to customers. Bringing the same care to year-end tax and cash decisions can protect the business through the next demand cycle. For more information, see US tax services for businesses, self-employed tax resources, US corporate tax and small business resources.
About the author: Dellendo Farquharson writes about tax, accounting and cash flow for owner-managed businesses at BOMCAS Canada. LinkedIn: https://www.linkedin.com/in/dellendo
BOMCAS Canada, 6063 – 88 St NW, Edmonton, Alberta T6E 5T4 | 780-667-5250 | info@bomcas.ca | https://bomcas.ca | https://bomcas.com
We'd like your Feedback!
If this information has been useful, please send us a note, we’d like to hear from you. If you’ve found different ways to navigate year end tax and cash planning we’d like to know that too!
Send email to: editor@shootingindustry.com
Get The Dealer Advantage Every Week!
By submitting this form, you are consenting to receive marketing emails from: . You can revoke your consent to receive emails at any time by using the SafeUnsubscribe® link, found at the bottom of every email. Emails are serviced by Constant Contact